An Open Internet Stack: What to Build, in What Order, and Why
Stefane Fermigier (Abilian) · sf@abilian.com
Draft working paper v0.8, 2026-09-23. Measurement and policy analysis on the programme's published instruments; each computed number is reproduced by the verification suite from the repository's data and each market and macro figure cites a fetched public source with URL, access date, and confidence flag (data/market-anchors-v1.csv). The taxonomy has one revision by its author; each tally is reported with and without it (Block 15, Section 4.4). The classes rest on reach coverage, with the other measured quantities reported as description (Section 5). The per-euro intervention ranking is anchored at instrument-family level from public cost records; the block-level ranking awaits per-block cost data.
Abstract
Building-block lists for European digital infrastructure name what the stack needs; they cannot tell which block to fund first, or with which instrument. This paper converts one such list, the fourteen Technological Building Blocks (TBBs) of Fermigier (2025), into a criterion that discriminates block by block, composing measured structure with sourced market economics. Each block is scored on a 52-category dependency graph with typed jurisdictional-reach edges, an exact cut calculus, service-level exit-friction scores, and a four-class rule (adequate, thin, captured, absent) frozen before any number was computed. Under the floor the rule reduces to one discriminating input: whether all categories in a block have a US or China jurisdictional-reach edge, with worst-level concentration a second trigger for two blocks. The option and coercion numbers, the exit-friction scores, and forkability are reported per block and read by the variants; they decide no class. Each block also comes with its economic rationale and, where public data exists, a sourced European market size and EU-provider share (45 anchor rows, each with source, URL, access date, and confidence flag). Eight of thirteen scored blocks have a published market size, ten of thirteen a share or proxy, and the remaining cells read "no published figure found".
The results follow. First, the classification separates the blocks: on the published fourteen, five classify captured (identity, cybersecurity supply, operations tooling, development tooling, market platforms) and seven thin, and the revision's fifteenth block makes it six captured. The market table is a second reading, independent of the first: it prices what rides on each block, and it does not track the classes. Non-EU shares at or above the captured blocks' sit among the thin blocks as well. Cloud stands at 70 percent for the US hyperscalers against 15 percent for EU providers; there is no EU browser-engine share. One incumbent holds 73 to 80 percent of EU public-sector productivity software; more than 85 percent of GenAI value-chain funding flows to US firms. The captured boundary is set by whether all categories in a block have a jurisdictional-reach edge, which is unrelated to market share. Two captured verdicts rest entirely on jurisdictional reach into forkable open-source substrate. These are stewardship gaps, priced per component by public cost anchors three orders of magnitude below a build-or-buy programme envelope.
Second, contracting the dependency graph onto the blocks gives the stack an economic geometry, computed and cross-checked in the suite. Seven blocks are net suppliers, with dependencies concentrated on the silicon chain, the development toolchain, network infrastructure, and operations tooling (raw in-degrees 15, 11, 10, 10 against out-degrees of 1 to 4). The application and AI blocks are pure consumers (in-degree 0) and cloud is the hinge (in 9, out 18). The platform block's supplier position is market access (6 of its 7 inbound edges are distribution edges), locating the rent at the door to users. The demand layer's measured edges concentrate on cloud and applications, touch identity exactly once (one enterprise-demand edge), and never land on AI foundations, operations, or development tooling, so procurement sees the top of a cone with exposure that arrives by composition.
Third, the downstream stake is macroeconomic and sourced. 83 percent of European business cloud and software spending, about EUR 330bn of 400bn a year, goes to US vendors (Asterès for Cigref, a study commissioned by a buyer association and flagged as such). Open-source software accounts for a Commission-estimated EUR 65 to 95bn of economy-wide EU GDP impact (Blind et al. 2021), drawn into the stack through the unpriced substrate of the two stewardship-gap blocks.
Fourth, the verdicts are stable under a 500-draw perturbation of each ordinal coding the rule reads. A pre-stated reach-edge perturbation locates the residual weight: four of the six captured verdicts ride on one or two single-coder reach edges and track edge survival.
Beneath all of this sits a uniform floor: each block has option number $N = 1$ and coercion number $\kappa = 1$, and five blocs (the United States, China, Japan, Korea, Taiwan) are each solo cutters for each block, because the unique minimal trace crosses the semiconductor floor. No block can be adequate in isolation and per-block checklists cannot certify the stack. The pre-stated above-floor variant shows the five-bloc structure is the floor's contribution, with the United States the sole residual solo cutter everywhere except the end-user block, which China also cuts. The classes map onto instrument families (build-or-buy, substrate stewardship, demand aggregation and maintenance, floor capacity), each mapping conditional on compute-floor policy. Public cost records give the per-euro criterion coarse family-level anchors in pairwise disjoint ranges (from about EUR 10^5 per stewardship engagement to over 10^10 for floor capacity); the block-level ranking awaits per-block cost data.
Keywords: digital sovereignty, open internet stack, technological building blocks, dependency networks, market structure, option sets, open-source software, public procurement.
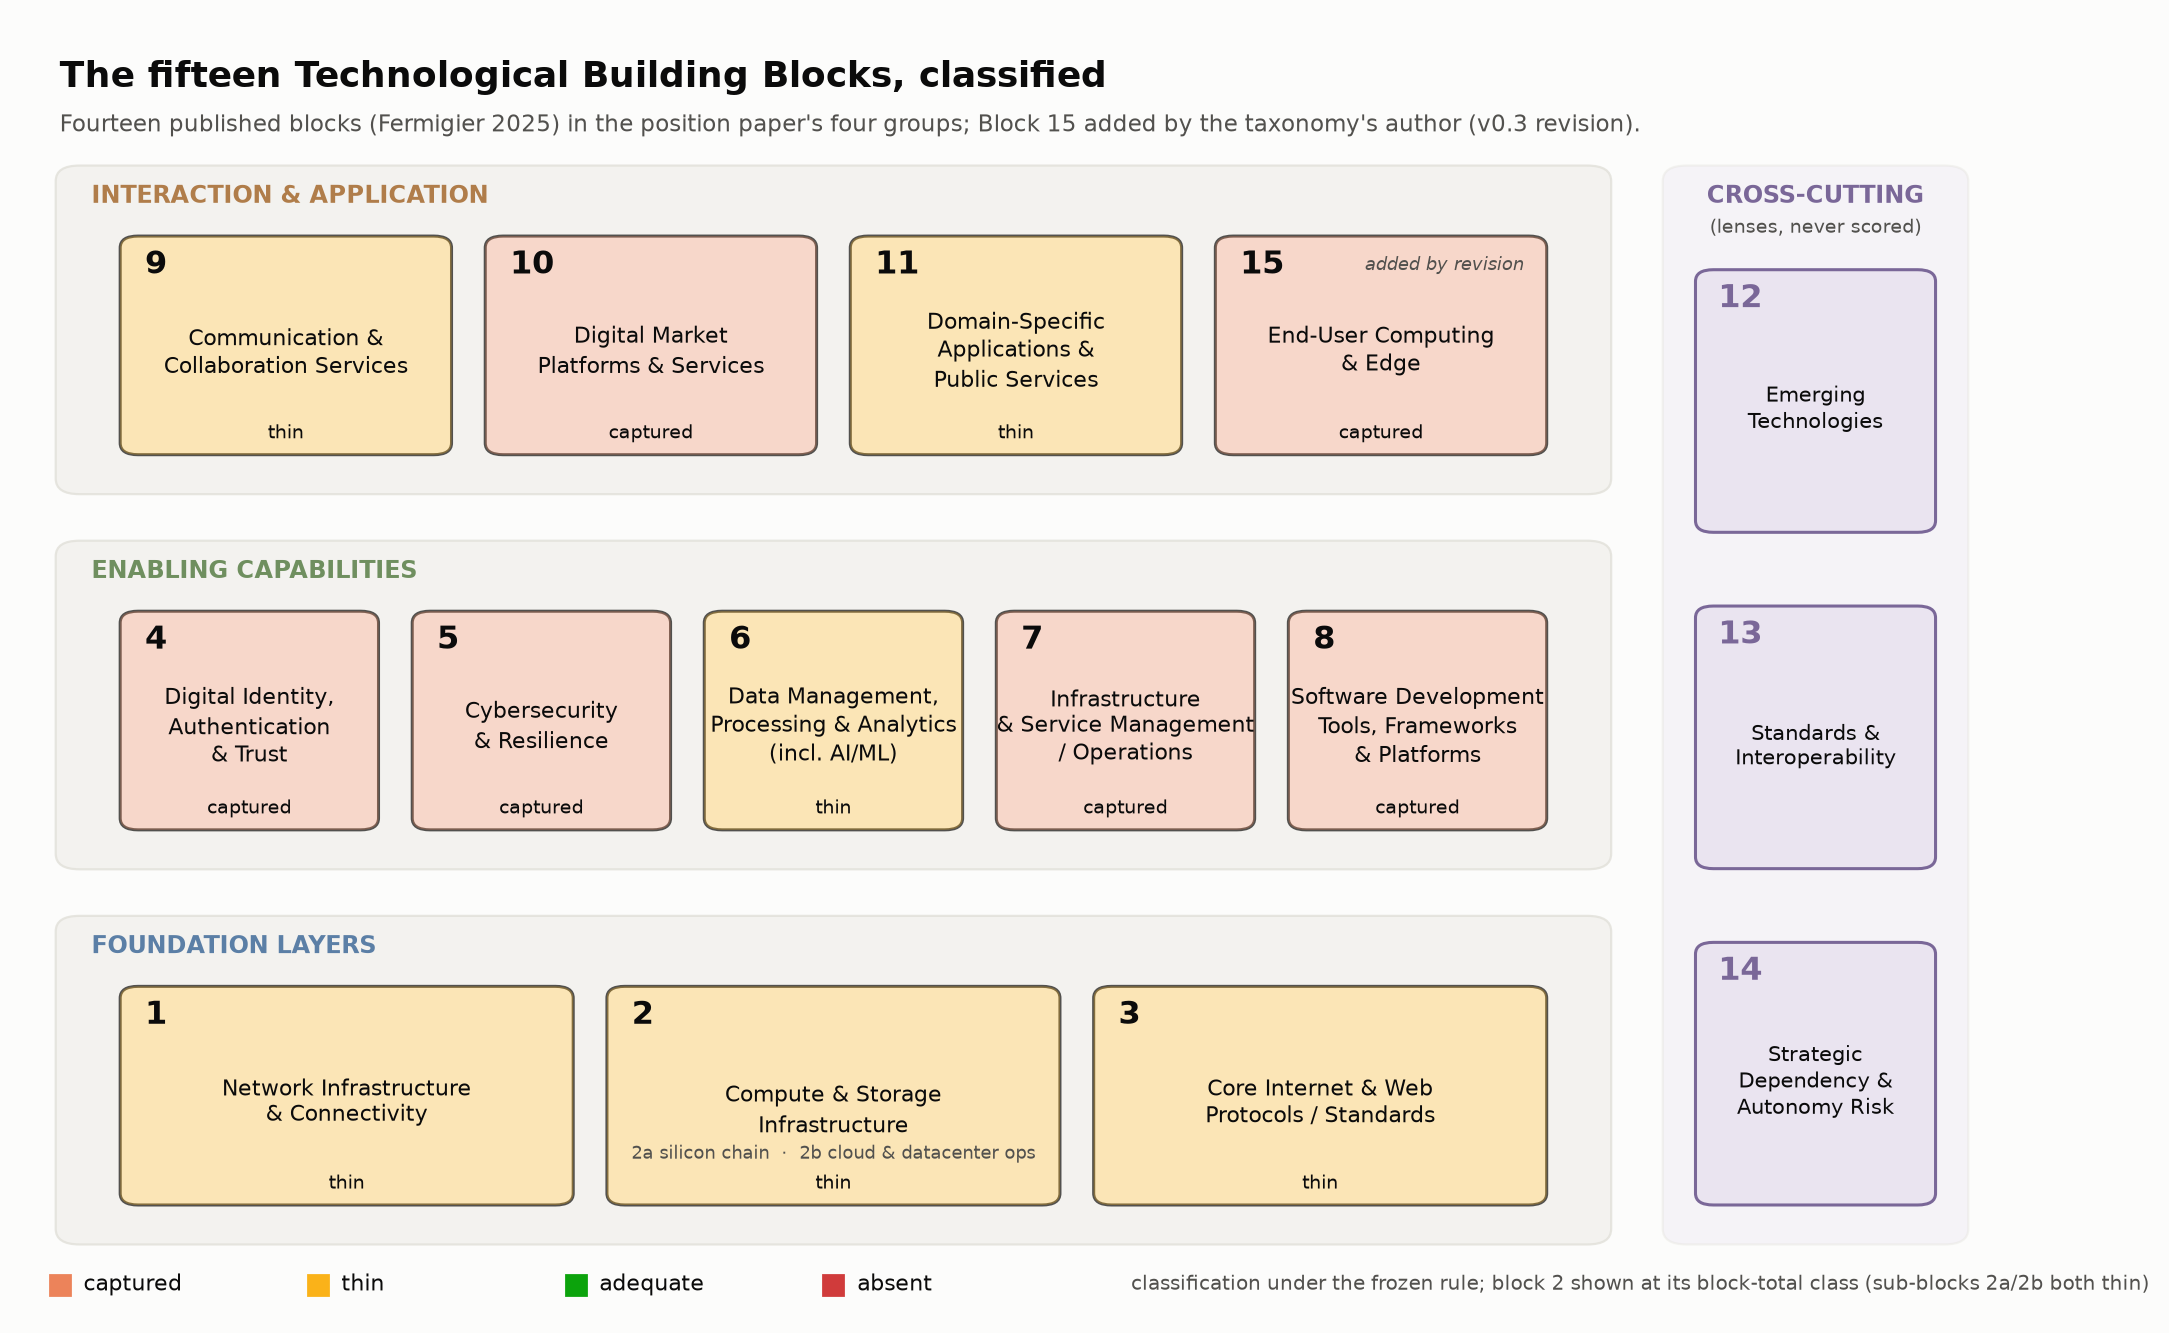
The fifteen technological building blocks under the frozen classification rule: which are captured, and which keep a forkable option.
About this paper
| Programme | Open Internet Stack |
| Genre | Draft working paper |
| Version | v0.8 |
| Date | 2026-09-23 |
| Full text | |
| Plain-language explainer | The stack behind the invoice |
Cite this paper
Fermigier, S. (2026). An Open Internet Stack: What to Build, in What Order, and Why.
Draft working paper v0.8, Abilian Econ Lab.
https://econ.lab.abilian.com/papers/tbb-criterion/