Leverage Without Additionality: What Co-Funding Ratios Identify in Public Technology Programmes
Stefane Fermigier (Abilian) · sf@abilian.com
Draft working paper v0.5, 2026-10-21. Three propositions, each with a proof and a numeric cross-check against brute force, and a remark; the ranking claim has a Monte-Carlo report. The application is an accounting exercise on published programme data and signed grant records; no causal effect is estimated and none is claimed.
Abstract
European technology programmes report a "leverage factor": the co-funding declared by grant beneficiaries per euro of public contribution. The statistic is presented as evidence that public money mobilizes private money.
We show what it identifies. Under a published co-funding schedule, the ratio is a deterministic function of that schedule, so a programme funding half of each project reports a leverage of exactly one whenever its beneficiaries declare the match the rate requires, whatever they would have invested anyway. The reported ratio bounds the crowding-in ratio from above, with equality only under the assumption that no beneficiary would have invested anything absent the grant. The caveat funders attach concerns a different quantity: their exclusions make the ratio a lower bound on the investment it counts, while the verb they attach to it claims crowding in, which the ratio bounds only from above. Compliance with the schedule cannot produce a ratio above a computable ceiling, so only observations above that ceiling reveal behaviour: a declaration in excess of the rule, which may or may not be additional. Because declared co-funding pools public and private sources, a rationale resting on private capital-market frictions is addressed only by the private component, which must be reported separately or the statistic is silent on the stated market failure.
We apply the results to the Digital Europe Programme, using the study prepared for the Commission and the 820 signed grants the Commission publishes. The headline leverage of 0.79, which the grant records reproduce, lies below the ceiling of one that the programme's lowest funding rate, 50 percent, implies, so it says nothing about behaviour; what it recovers is a bound on programme composition, at most 0.21 of the envelope disbursed at full funding rates, against 0.15 in the records. The records also show where declarations exceed the rule: 57 grants declare more co-funding than their rate requires, EUR 68 million in all or 3.3 percent of declared co-funding, two-thirds of it in digital innovation hubs that member states designate and in one pilot of the European digital identity wallet. Private money is about 29 percent of declared co-funding across the twelve technology areas where both series are published; in artificial intelligence it is 9.1 percent of reported leverage, and in advanced connectivity none. Programmes sharing one schedule report an identical ratio while true additionality spans the whole admissible range. Across schedules, ordering by the reported ratio inverts the ordering by true additionality on a share of pairs set by how dispersed counterfactual investment is, 5 to 30 percent under the priors tried.
Keywords: additionality, crowding in, state aid, subsidy design, programme evaluation, technology policy.
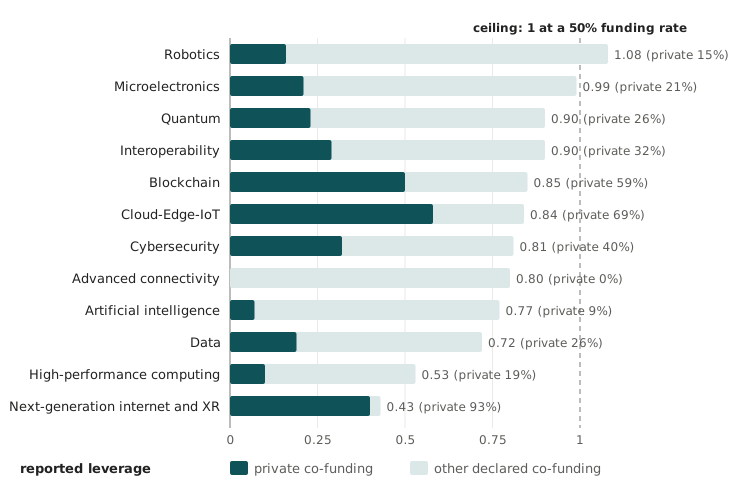
Reported leverage of the Digital Europe Programme by technology area, with its private component. Only one area exceeds the ceiling that compliance with the funding schedule implies, and only there does the ratio say anything about behaviour.
About this paper
| Programme | Game theory |
| Genre | Draft working paper |
| Version | v0.5 |
| Date | 2026-10-21 |
| Full text | |
| Plain-language explainer | The leverage that was already in the rules |
Cite this paper
Fermigier, S. (2026). Leverage Without Additionality: What Co-Funding Ratios Identify in Public Technology Programmes.
Draft working paper v0.5, Abilian Econ Lab.
https://econ.lab.abilian.com/papers/leverage-without-additionality/